
Ludlow Exchange LLC, operator of sports prediction market Novig, sued Wisconsin Attorney General Josh Kaul and state gaming administrator John Dillett in the U.S. District Court for the Western District of Wisconsin, seeking to block the state from treating its sports event contracts as illegal gambling under Wisconsin’s commercial gambling statutes.
The 45-page complaint, filed before Wisconsin could bring its own action, comes just over a week after Novig began offering contracts to Wisconsin residents. Novig says the preemptive filing was necessary because Wisconsin has already sued rival operators over near-identical contracts, and it is seeking preliminary relief to prevent enforcement while the case proceeds.
Wisconsin opened its campaign against event-contract trading in April, suing Kalshi, Polymarket, Robinhood, Crypto.com and Coinbase over sports-related contracts it alleges violate state gambling law and constitute a public nuisance. Novig is now the fifth state defendant the operator has named in federal court since August 4, following earlier suits against New York, New Mexico, Massachusetts and Washington.
The dispute turns on federal preemption. Novig argues its contracts are swaps under the Commodity Exchange Act, placing them under the exclusive jurisdiction of the Commodity Futures Trading Commission via CEA §2(a)(1)(A), with §1a(47) defining “swap” broadly and §16(e) addressing preemption of conflicting state requirements. Ludlow Exchange was designated a CFTC-regulated contract market on June 16, a status Novig says shields its Wisconsin offering from state gambling enforcement.
Courts have split on the theory. The Third Circuit found in KalshiEX LLC v. Flaherty that the CEA preempted New Jersey’s gambling law for Kalshi’s sports contracts, while a Nevada federal court reached the opposite conclusion at the preliminary stage in North American Derivatives Exchange v. State of Nevada. That divide echoes the wider split among federal courts over prediction-market jurisdiction.
Novig also faces an unfavorable precedent from within Wisconsin itself. A federal judge rejected the CFTC’s own request for a preliminary injunction against the state, finding the agency had not met the evidentiary bar for its preemption theory, according to SBC Americas. That case remains pending and does not resolve Novig’s separate suit, but it signals the uphill argument any operator faces before Wisconsin courts, a pattern also visible in Kalshi’s parallel preemption challenge over state gambling enforcement.
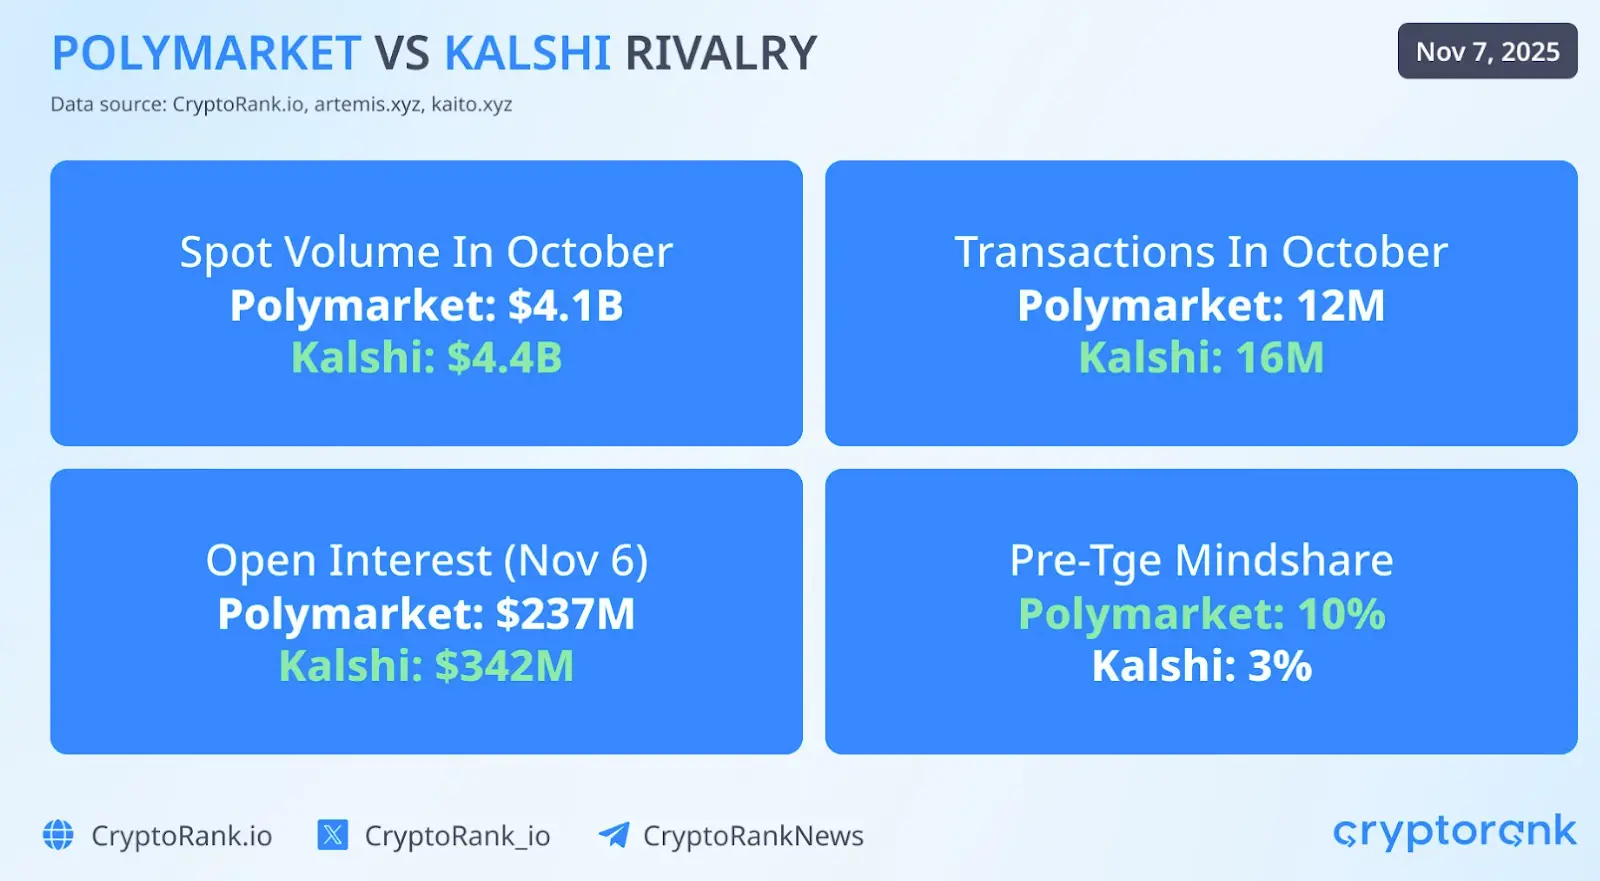
Novig is positioning itself apart from Kalshi and Polymarket by restricting its marketplace to sports contracts, requiring users to be at least 21, and pairing its legal campaign with a marketing agreement making it the first MLB team partner, branding Citi Field and broadcasts for the New York Mets. Crypto-linked volume on Kalshi and Polymarket alone reached $1.46 billion, 15.4% of tracked prediction-market activity, according to Artemis data showing total sector volume hit $9.50 billion on August 16 – 67 times the $139.8 million recorded a year earlier.
Source: Cryptopolitan

Petra Vanhoof has spent the better part of a decade following the shifting tides of gambling regulation across Europe and beyond. She came up through the compliance side of the industry before pivoting to writing, which gives her a grounded, no-nonsense perspective on the rules, loopholes, and political maneuvering that shape how operators actually do business. She is particularly drawn to the gap between what regulators say and what the market ends up doing in response.