
The Commodity Futures Trading Commission issued a staff advisory on September 22 warning that prediction-market contracts tied to whether a prominent individual will utter a specific phrase during a public appearance carry a heightened risk of manipulation. The advisory applies to so-called mention markets offered by designated contract markets operating in the United States.
Mention contracts settle on the discrete conduct of a single person, a structure the CFTC says may be neither independently generated nor externally verifiable. The advisory follows the regulator’s decision last month to ban a former White House teleprompter operator from trading on prediction markets for three years, amid allegations that Gabriel Perez used advance knowledge of Donald Trump’s speeches to place risk-free trades on mention markets tied to the president’s remarks.
No New Rule, No Penalty
The CFTC’s memo tells exchanges interested in listing mention markets to put in place prophylactic trading rules designed to detect and deter manipulation. The agency has been explicit that the advisory is not intended to create enforceable rights, whether substantive or procedural, and does not amount to a no-action position that could be relied upon to establish new binding rules or regulations.
Prediction markets are categorised as Designated Contract Markets under CFTC oversight, a status that obliges operators to comply with 23 core principles set out in the Commodity Exchange Act. Chief among them for this advisory is Core Principle 3, which bars DCMs from listing contracts that are readily susceptible to manipulation – the standard against which the CFTC now expects mention markets to be measured. Readers can find related coverage in the agency’s oversight of self-certified prediction contracts listed on other exchanges.
Separate From State Litigation
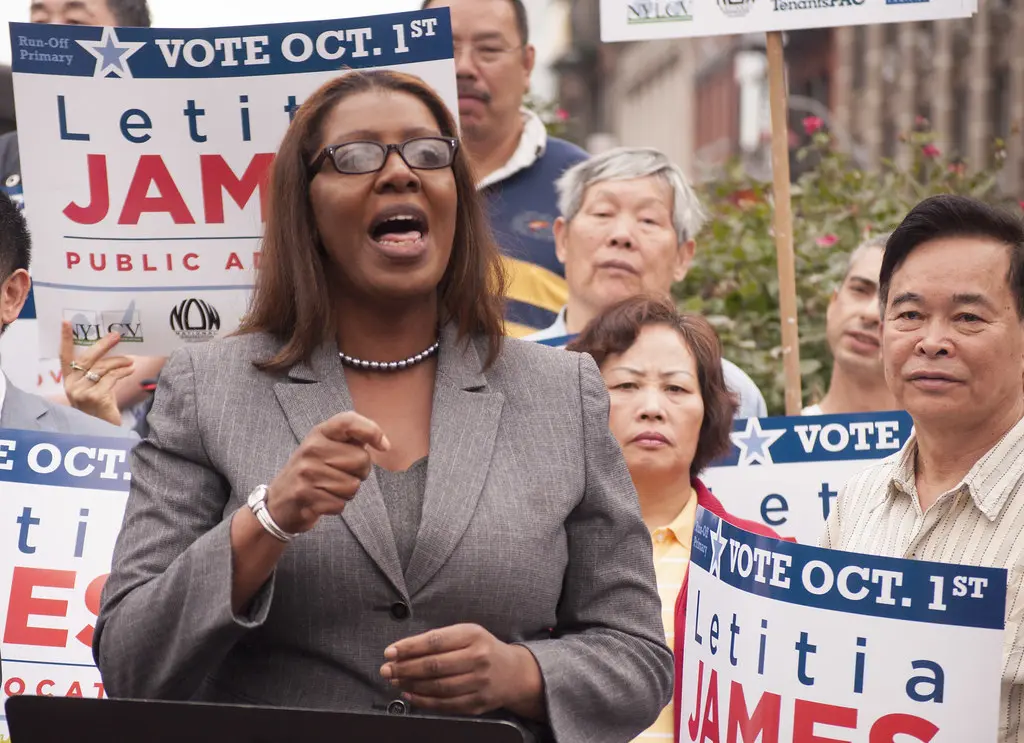
The advisory is a federal, CFTC-level intervention and stands apart from the state-level fight playing out in New York, where Attorney General Letitia James has sued Polymarket over an alleged illegal gambling operation, adding to her earlier case against Kalshi. That litigation concerns New York’s allegation that Polymarket ran an illegal gambling operation, while the CFTC advisory addresses contract design and manipulation risk – a divide explored further in coverage of the competing state and federal views on prediction-market oversight.
For operators, the practical effect is a heavier compliance lift rather than an outright prohibition. Exchanges weighing mention contracts now face an expectation that they build surveillance and detection mechanisms into product design from the outset, a bar some platforms have already cleared in other contexts, such as Novig’s approval process before launching in the US market. The CFTC has stopped short of banning mention markets outright, and DCMs considering listing them would need to meet the advisory’s expectations.

Renata Kovacs has spent the better part of a decade following the regulatory shifts and licensing battles that define how gambling markets open, close, and evolve across Europe and beyond. She came up through the legal and compliance side of the industry before shifting her focus to journalism and analysis, giving her a perspective that sits closer to the operator room than the press box. Her coverage tends to cut through the noise and get straight to what a regulatory change actually means for the businesses and players involved.